H.R. 7561: Local Infrastructure Tax Cuts Act
Sponsor
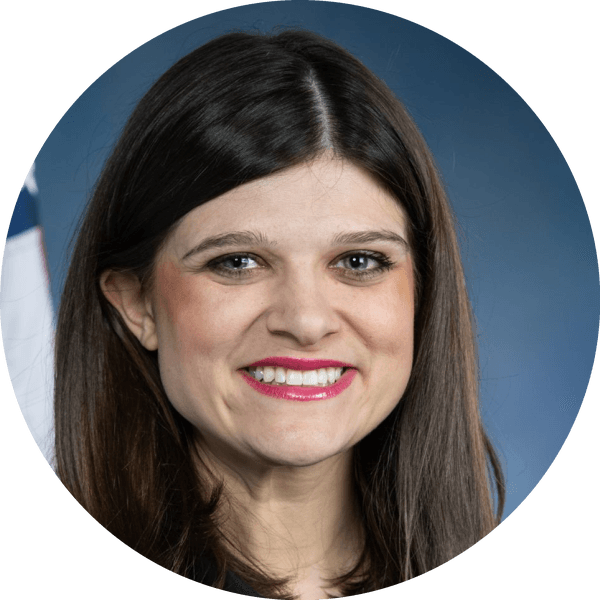
Haley Stevens
Democrat · MI-11
Local infrastructure assessments deserve a federal tax break
Why it matters
$215,000 is the line for married couples: one dollar over it and H.R. 7561 takes your state and local tax deduction to $0. Below the line, the cap drops from roughly $40,000 under the 2025 tax law to $10,000, and special assessments for local roads, sewers, and utilities on your home would count toward it for the first time.
H.R. 7561 does two things to the deduction for state and local taxes, known as SALT. It creates a new category of deductible local tax, and it tightens the limit on the whole deduction.
The new category is the special assessment. Cities, townships, and counties often pay for a specific project, such as a sewer extension, a repaved road, or a stormwater system, by charging only the properties it serves. Federal tax law has long treated those charges as an investment in your property rather than a tax, so they aren't deductible. Under H.R. 7561, a special assessment on your principal residence would count as a deductible state and local tax.
Qualifying projects include transportation, schools, hospitals, police and fire stations, water and sewer lines, electric, gas, and telecom utilities, and dam restoration. The project has to be owned by a state or local government, or by a not-for-profit, member-owned utility such as a rural electric co-op, and it has to directly benefit the property being charged.
The second change is to the cap. The 2025 tax law raised the SALT limit to $40,000, rising about 1% a year, and began phasing it down only above roughly $500,000 of income. This bill replaces that. Most filers would be limited to $10,000, and married people filing separately to $5,000. Special assessments would share that same cap with your property, income, and sales taxes.
Above an income threshold, the deduction disappears completely: $215,000 for married couples filing jointly, $161,250 for heads of household, and $107,500 for everyone else. There is no phase-out. A couple at $215,000 keeps up to $10,000; a couple at $215,001 keeps nothing.
All of these dollar figures would be adjusted for inflation starting in 2028. The changes would apply to tax years beginning in 2027.
Bill Progress
Latest Action · Feb 12, 2026
Referred to the House Committee on Ways and Means.
H.R. 7561 Bill Summary
What H.R. 7561 actually does.
Special assessments on your home become deductible
Local charges levied on properties in a special assessment district to pay for a project that directly benefits them, such as sewer, road, or stormwater work, would count as deductible state and local taxes. Only assessments on your principal residence qualify.
A wide range of public projects qualify
Eligible projects include transportation, schools, hospitals, police, fire, and emergency facilities, water, wastewater, stormwater, telecom, electric, and gas utilities, and dam restoration. The project must be owned by a state, territory, local government, D.C., or a not-for-profit, member-owned utility.
The SALT cap drops to $10,000
Filers under the income threshold could deduct up to $10,000 in combined state and local taxes, including any qualifying special assessments. Married people filing separately would be capped at $5,000. That replaces the roughly $40,000 cap in current law.
Higher earners lose the deduction outright
Above $215,000 for joint filers, $161,250 for heads of household, and $107,500 for other filers, the SALT deduction becomes $0. The cutoff is a cliff, not a gradual phase-out. Income for this test includes foreign earnings that are otherwise excluded from tax.
Limits rise with inflation from 2028
The $10,000 and $5,000 caps and all three income thresholds would be indexed to inflation for tax years beginning after 2027. Both halves of the bill take effect for tax years beginning in 2027.
Who benefits from H.R. 7561?
Homeowners paying off a neighborhood improvement
If your property tax bill includes an assessment for a new water main, sidewalk, or road reconstruction on your primary home, that charge could be deducted for the first time, as long as you itemize and your total state and local taxes stay under $10,000.
Lower-cost areas where SALT bills run under $10,000
Itemizers whose property and income taxes don't fill the $10,000 cap would gain room to deduct assessments. At a 22% bracket, a $1,200 yearly sewer assessment would cut federal tax by about $264.
Rural co-op and small-town utility customers
Projects owned by not-for-profit, member-owned utilities count, so assessments tied to co-op electric, broadband, or water expansions could qualify alongside those from towns and counties.
The federal Treasury
Cutting the cap from about $40,000 to $10,000 and ending it above $215,000 would raise federal revenue. No official estimate has been published.
Who is affected by H.R. 7561?
Households above the income cutoffs
A married couple earning over $215,000, or a single filer over $107,500, would lose the SALT deduction entirely, including any new special assessment deduction. The bill's thresholds are far lower than the roughly $500,000 at which the current cap starts shrinking.
Itemizers in high-tax states under the cutoff
A couple earning $180,000 in New Jersey with $22,000 in property and income taxes can deduct all of it today. Under H.R. 7561 they could deduct $10,000.
People whose taxes already exceed $10,000
Special assessments share the same cap as property and income taxes. If you're already at $10,000, a new assessment adds nothing to your deduction.
Owners of second homes, rentals, and land
The special assessment deduction applies only to your principal residence.
HR7561 Legislative Journey
House: Committee Action
Feb 12, 2026
Referred to the House Committee on Ways and Means.
About the Sponsor
Haley Stevens
Democrat, Michigan's 11th congressional district · 7 years in Congress
Committees: Science, Space, and Technology, House Select Committee on the Strategic Competition Between the United States and the Chinese Communist Party, Education and Workforce
View full profile →
Cosponsors (3)
All 3 cosponsors are Democrats. Cosponsors represent 1 state: Michigan.
Committee Sponsors
Ways and Means Committee
0 of 45 committee members cosponsored
No committee members have cosponsored this bill
19 Democrats across this committee haven't cosponsored yet. Mobilize their constituents
What laws does H.R. 7561 change?
1 changes
Sections Amended
Section 164(a) of Internal Revenue Code of 1986
inserting after paragraph (4) the following new paragraph: ``(5) Qualified special assessment taxes
H.R. 7561 Quick Facts
- Committee
- Ways and Means
- Chamber
- House
- Policy
- Taxation
- Introduced
- Feb 12, 2026
Referred to the House Committee on Ways and Means.
Feb 12, 2026
Official Sources
Official bill text, sponsors, and status for the Local Infrastructure Tax Cuts Act.
The section of the Internal Revenue Code that H.R. 7561 amends to add special assessments and rewrite the SALT cap.
The IRS explanation of the current $40,000 SALT limit and why local benefit assessments are not deductible today.
Explains the current rule that assessments for streets, sidewalks, and water and sewer systems cannot be deducted.
Where itemizers claim state and local taxes, including the current cap and its phase-down above $500,000 of income.
The 2025 tax law that raised the SALT cap to $40,000, which H.R. 7561 would replace.
The committee H.R. 7561 was referred to, and where it would need to advance.
H.R. 7561 Common Questions
Does H.R. 7561 raise or lower the SALT cap?
Lower. The 2025 tax law set the cap at about $40,000. H.R. 7561 would bring it back to $10,000, or $5,000 if you're married filing separately, and to $0 above its income cutoffs.
What income would make me lose the SALT deduction entirely?
Above $215,000 for married couples filing jointly, $161,250 for heads of household, and $107,500 for single filers and married people filing separately. Those amounts would rise with inflation starting in 2028.
Is there a phase-out, or do you lose it all at once?
All at once. A couple at $215,000 can deduct up to $10,000; a couple at $215,001 deducts nothing. In the 24% bracket, that one dollar costs about $2,400 in tax.
Are special assessments tax deductible?
Not today. Federal law treats assessments for local improvements as adding value to your property. H.R. 7561 would let you deduct them on your principal residence if they fund a qualifying public project that directly benefits your home.
What local projects would qualify?
Transportation, schools, hospitals, police, fire, and emergency facilities, water, sewer, stormwater, electric, gas, and telecom utilities, and dam restoration. The project must be owned by a government or a not-for-profit, member-owned utility.
Does the special assessment deduction count toward the $10,000 cap?
Yes. Assessments share the cap with your property, income, and sales taxes. If those already reach $10,000, a new assessment won't increase your deduction.
Can I deduct an assessment on a rental or vacation home?
No. The bill limits the new deduction to your principal residence.
When would H.R. 7561 take effect?
For tax years beginning January 1, 2027, so the first returns affected would be filed in 2028.
Based on H.R. 7561 bill text
H.R. 7561 Bill Text
“To amend the Internal Revenue Code of 1986 to modify the limitation on individual deductions for certain state and local taxes and to allow a deduction for qualified special assessment taxes, and for other purposes.”
Source: U.S. Government Publishing Office
Get notified when H.R. 7561 moves
Committee votes, floor action, cosponsor changes — straight to your inbox.
Bill alerts + Legisletter's monthly briefing. Unsubscribe anytime.
Taxation Bills
9 related bills we're tracking
American Family Act
Referred to the House Committee on Ways and Means.
Apr 9, 2025
Freedom to Invest in Tomorrow’s Workforce Act

Referred to the House Committee on Ways and Means.
Feb 7, 2025
Main Street Tax Certainty Act
Referred to the House Committee on Ways and Means.
Jan 23, 2025
Death Tax Repeal Act
Referred to the House Committee on Ways and Means.
Feb 13, 2025
To amend the Internal Revenue Code of 1986 to modify the railroad track maintenance credit.
Referred to the House Committee on Ways and Means.
Jan 16, 2025
Tax Fairness for Workers Act
Referred to the House Committee on Ways and Means.
Apr 7, 2025
Health Care Affordability Act of 2025

Referred to the House Committee on Ways and Means.
Jan 9, 2025
Affordable Housing Credit Improvement Act of 2025
Referred to the House Committee on Ways and Means.
Apr 8, 2025
More Homes on the Market Act
Referred to the House Committee on Ways and Means.
Feb 13, 2025
Trending Right Now
Bills gaining momentum across Congress
ASAP Act
Ordered to be Reported in the Nature of a Substitute by the Yeas and Nays: 40 - 0.
Sep 16, 2026
761st Tank Battalion Congressional Gold Medal Act
Referred to the Committee on Financial Services, and in addition to the Committee on House Administration, for a period to be subsequently determined by the Speaker, in each case for consideration of such provisions as fall within the jurisdiction of the committee concerned.
Feb 26, 2025
Federal Firearms Licensee Protection Act of 2025
Referred to the House Committee on the Judiciary.
Mar 3, 2025
Tracking Taxation in Congress? Monitor bills, track cosponsor momentum, and launch advocacy campaigns — all from one advocacy platform.